

How a sunken Spanish galleon set off London's first stock market boom, and how the boom ended
In June 1687 a ship called the James and Mary came up the Thames carrying roughly 32 tons of silver and jewels. Her captain was William Phips, a New England shipwright turned treasure hunter, and the cargo had spent forty-six years on a reef north of Hispaniola inside the wreck of the Nuestra Señora de la Concepción, the almiranta of the Spanish plate fleet of 1641.
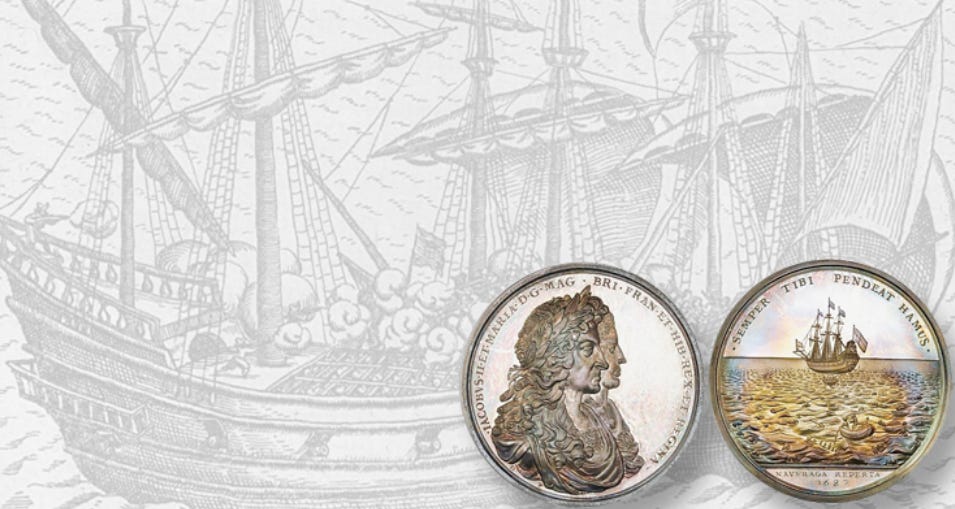
The official valuation of what Phips brought home was over £207,600. Phips himself took away more than £11,000.1 The syndicate behind him, assembled by Christopher Monck, second Duke of Albemarle, had put up a comparatively trivial sum, and the return quoted ever since is 10,000 per cent2 — contemporary records of the syndicate's subscription vary, so the precise multiple should be treated as approximate. Even a heavily discounted version of that number would have been the financial event of the decade.
What made it combustible was the scale of the payout relative to ordinary English incomes. Gregory King's social table for 1688, in the version revised by Peter Lindert and Jeffrey Williamson in Explorations in Economic History in 1982, gives 2,000 families of greater merchants trading by sea an average income of £400 a year. Labouring people and outservants got £15. King's own £2,800 average for a temporal lord is revised upward by Lindert and Williamson to £6,060.3 Phips, on one voyage, had banked something close to twenty-seven years of a top merchant's income, and nearly twice what an English peer took in a year. He was knighted, and later became governor of Massachusetts.
A market with almost nothing in it
The London that received this news barely had a stock market to speculate in. There were fewer than fifteen English joint-stock companies in existence in 1687. When John Houghton began printing share prices in A Collection for Improvement of Husbandry and Trade in March 1692, he could list only eight: the East India Company, the Royal African Company, the Hudson's Bay Company, the Linen Company, the Glass-Makers, the White Paper Company, the Company of Copper Miners, and a wreck-diving company.4
Then the floodgates opened. W. R. Scott, whose census of English, Scottish and Irish joint-stock companies remains the standard count, found more than a hundred new English companies established between 1688 and 1695.5 Within roughly seven years the market went from a curiosity for a few hundred City men to something a country gentleman could read about in a weekly trade paper.
The infrastructure arrived just as quickly. The brokerage book of Charles Blunt, covering 1692 to 1695, records 155 clients, only 22 of whom had been shareholders in the established companies in 1688. Two-thirds of them traded derivatives. Of the forty who dealt ten times or more, exactly one never touched an option.6 This was a brand new investor base, and it went straight to the complicated instruments.
The technology story
Every boom needs a story about the future, and the 1690s had the diving engine.
Christine MacLeod set out the numbers in “The 1690s Patents Boom: Invention or Stock-Jobbing?” in the Economic History Review in 1986. Five patents for diving engines were issued between 1672 and 1689. Between the autumn of 1691 and late 1693, seventeen petitions were filed and eleven enrolled. Diving engines alone accounted for almost a fifth of every patent issued in England in 1691 to 1693.7
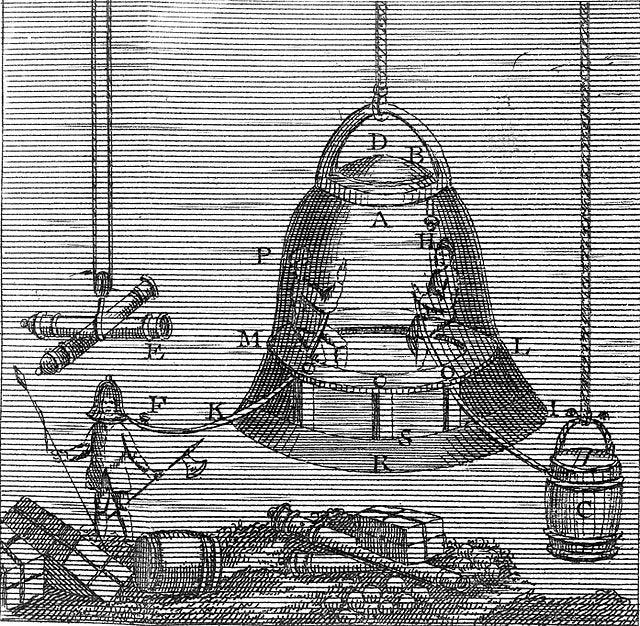
The pitch was straightforward. Phips had found his wreck the hard way, with breath-holding divers and luck. A patented diving bell or diving suit would keep a man under water longer, which meant more wrecks, faster, and with less dependence on the miraculous. The patent was the credential. As one observer noted in 1695, “a patent gives a reputation to it.”
Not all of it was fraud. Edmond Halley, already known for the comet, built a diving bell of his own and worked it over the Guynie Frigott, a Royal African Company ship lost off Pagham in the spring of 1691. He kept three men at ten fathoms for an hour and three quarters. His real contribution was the resupply method, weighted casks of air lowered from the surface and vented into the bell, and it is genuine engineering rather than prospectus language. The venture still did not pay. That is the pattern of the decade in miniature: the technology sometimes worked, and the business almost never did.
Never sure were any men of common sense embarked in a more unpromising adventure; 'twas above a million to one against them.
— Aaron Hill, on Phips's original voyage
Of what followed, Hill wrote that through its success “a thousand families have been since undone, by sending their estates a diving after shipwrecked treasure.”8
Daniel Defoe was one of the undone. He lost £200 in John Williams's diving engine venture, and afterwards described himself as the cully, the mark. He went on to write An Essay upon Projects in 1697 and to give the decade the name that stuck: the Projecting Age.9
The recoveries never came. Expedition after expedition sailed and returned with, in the main, a few cannon.
The unwinding
The bubble did not die of embarrassment about diving bells. It died of a monetary crisis.
England's silver coinage had been clipped to the point of collapse. Full-weight silver in circulation fell from about £2.5 million in December 1693 to roughly £1 million by June 1695. William Lowndes, Secretary to the Treasury, proposed a 25 per cent devaluation. John Locke argued for a straight recoinage at the old standard, and Locke won the argument.
Parliament demonetised clipped coin in January 1696, and the Royal Mint could not produce replacements fast enough. The money supply fell from around £26 million in December 1695 to under £17 million six months later. The Land Bank, promoted as a rival to the two-year-old Bank of England, failed to raise its subscription. The Bank of England suspended redemptions from May to October 1696.10
The equity market went with it. Between 1692 and 1697, East India Company stock fell from £200 to £37. The Royal African Company went from £52 to £13. Hudson's Bay went from £260 to £80.11 These were the blue chips.
For the newer companies the arithmetic was blunter. Of the 140 English and Scottish companies trading in 1693, on Scott's count as cited by Edward Chancellor, only about 40 were still alive four years later.12 Every diving company had gone.
Parliament's response in 1697 was the Act to Restrain the Number and Ill Practice of Brokers and Stock-Jobbers, which licensed brokers, capped their number in the City of London at one hundred, and limited commissions. It is the first serious attempt at securities regulation in English law, and it was passed by men who had watched the whole thing happen.
Was it madness?
Edward Chancellor made the 1690s the opening act of Devil Take the Hindmost in 1999, and drew the modern parallel explicitly. “The modern investor,” he wrote, “is just as liable to be whipped up into a frenzy over companies introducing a new technology as the diving engine ‘cullies’ of the 1690s.”13 Reviewing the book for the Washington Post that September, Steven Mufson noted the irony that Max Weber had once held up the commercial energy of the age as evidence of the triumph of rationalism.14
Anne Murphy's account in The Origins of English Financial Markets, published by Cambridge in 2009, is the necessary corrective. Her investors are not lunatics. They price liquidity, they hedge, they use options with intent, and they hold the government to account over its debts. The failure of the diving companies is not proof that nobody was thinking. Plenty of contemporaries thought hard and still lost, which is a different and more uncomfortable finding.
Both readings can be true at once. A genuinely new asset class appeared in London in under a decade, financed a war, survived a monetary catastrophe, and left behind the Bank of England, a functioning secondary market and a printed price list. It also destroyed a great many families who bought the wrong story at the wrong moment.
The wreck-diving companies were the wrong story. The market that formed around them was not.
Notes
Sources
Origin. This article began from Jamie Catherwood's "Sunken Treasures" and "Speculation & Innovation" at Investor Amnesia, which assembled the Phips story and pointed to the diving-engine patent boom. Every figure below was then traced back to its underlying source, and where the two differ the archival or scholarly figure is the one used here.
1. “Phips, Sir William,” Dictionary of Canadian Biography, vol. 1. The valuation is the official one recorded on the treasure’s return; for the underlying accounts see R. H. George, “The Treasure Trove of William Phips,” New England Quarterly 6 (1933): 294-318.
2. The figure is standard in the popular literature and is repeated by Chancellor (see note 13). Contemporary records of the syndicate’s subscription vary, so the precise multiple should be treated as approximate.
3. Peter H. Lindert and Jeffrey G. Williamson, “Revising England’s Social Tables 1688-1812,” Explorations in Economic History 19 (1982): 385-408, table 2. The £400 and £15 figures are King’s own, retained by Lindert and Williamson; the £6,060 average for temporal lords is their upward revision of King’s £2,800.
4. Anne L. Murphy, “Investors in London’s First Stock Market Boom.”
5. W. R. Scott, The Constitution and Finance of English, Scottish and Irish Joint-Stock Companies to 1720, 3 vols. (Cambridge, 1910-12).
6. Murphy, “Investors in London’s First Stock Market Boom,” on the brokerage ledgers of Charles Blunt.
7. Christine MacLeod, “The 1690s Patents Boom: Invention or Stock-Jobbing?,” Economic History Review 39, no. 4 (1986): 549-71.
8. Aaron Hill, quoted in MacLeod, “The 1690s Patents Boom.”
9. Daniel Defoe, An Essay upon Projects (London, 1697).
10. On the recoinage and the Bank’s suspension see “Recoinage Crisis of 1696,” The Tontine Coffee-House, 29 November 2021, and James Narron and David Skeie, “Crisis Chronicles: The ‘Not So Great’ Re-Coinage of 1696,” Liberty Street Economics, Federal Reserve Bank of New York, 2013.
11. Price ranges as given in “Recoinage Crisis of 1696.”
12. Scott’s count, as cited in Chancellor, Devil Take the Hindmost.
13. Edward Chancellor, Devil Take the Hindmost: A History of Financial Speculation (New York: Farrar, Straus and Giroux, 1999).
14. Steven Mufson, “Great Expectations,” Washington Post, 12 September 1999.
15. Anne L. Murphy, The Origins of English Financial Markets: Investment and Speculation before the South Sea Bubble (Cambridge: Cambridge University Press, 2009).